Fixed, Variable or Split Home Loan: Which Is Right for You?
Fixed, Variable or Split Loan?
Choosing between a fixed, variable or split home loan affects much more than the interest rate you see on the day you apply. It can change how predictable your repayments are, whether you benefit from future rate reductions, how easily you can make extra repayments and whether features such as an offset account or redraw facility are available.
There is no loan type that is automatically best for every borrower.
A fixed-rate loan can provide repayment certainty for an agreed period but may limit flexibility.
A variable-rate loan can offer more features and freedom, but the rate and required repayments may change.
A split loan combines fixed and variable portions, giving you some certainty while retaining some flexibility.
The right decision depends on your budget, plans, savings, attitude towards changing repayments and the specific lender's product rules—not on trying to predict interest rates perfectly.
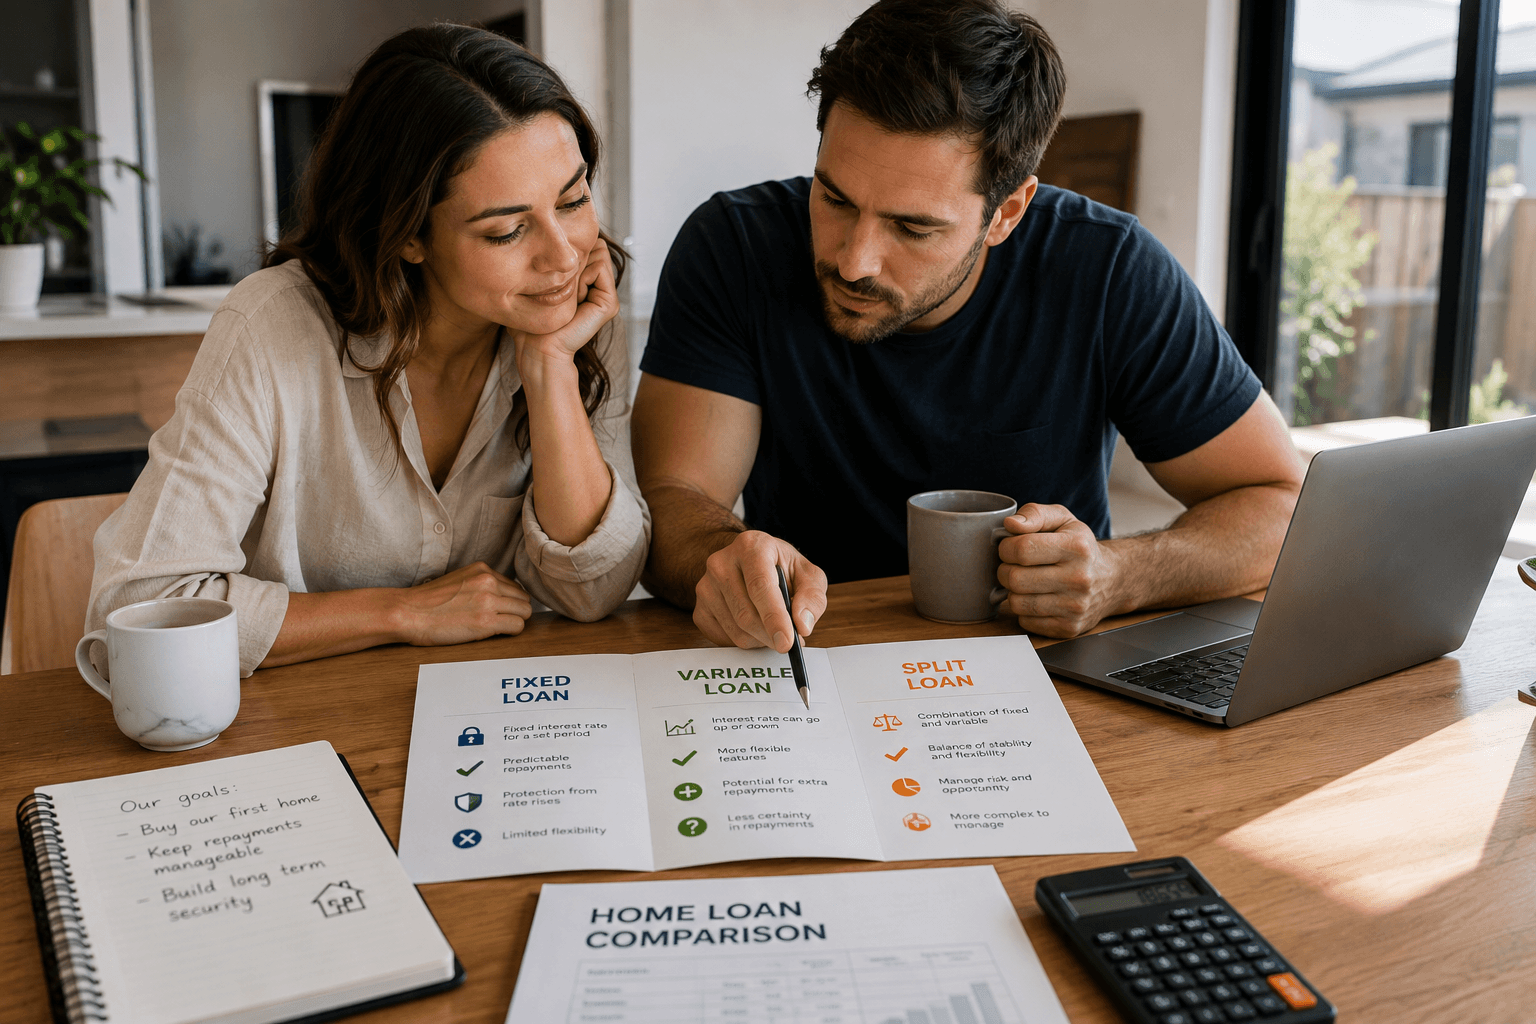
Fixed, Variable and Split Loans at a Glance
Feature | Fixed loan | Variable loan | Split loan |
|---|---|---|---|
Interest rate | Fixed for an agreed period | Can increase or decrease | Fixed on one portion and variable on the other |
Repayment certainty | Higher during the fixed period | Lower because repayments may change | Partial certainty |
Benefit if variable rates fall | No, during the fixed period | Generally yes, if the lender reduces your rate | Only on the variable portion |
Protection if variable rates rise | Yes, during the fixed period | No | Only on the fixed portion |
Extra repayments | Often limited | Commonly more flexible | Usually more flexible on the variable portion |
Offset account | Often unavailable or restricted | More commonly available on eligible products | May be available against the variable portion |
Redraw | Often unavailable or restricted | May be available on eligible products | May be available on the variable portion |
Cost to change or repay early | Break costs or other charges may apply | Generally more flexible, but fees can still apply | Fixed portion may attract break costs |
Best suited to | Borrowers prioritising short-term certainty | Borrowers prioritising flexibility | Borrowers wanting a balance of both |
This table is a general comparison only. Product features and conditions vary widely between lenders.
What Is a Fixed-Rate Home Loan?
A fixed-rate home loan locks in an interest rate for an agreed period, commonly between one and five years.[1] During that period, the rate on the fixed portion does not move with changes to the lender's variable rate.
For a principal-and-interest loan, this generally gives you a predictable required repayment during the fixed period, provided the loan is not varied and no other relevant charge changes.
Fixing the rate does not usually mean fixing it for the entire 25- or 30-year loan term. Once the fixed period ends, the loan will generally move to a variable rate unless you arrange another fixed period or refinance. The rate available at that time may be higher or lower than your original fixed rate.
Advantages of a Fixed Loan
More Predictable Repayments
The main benefit is certainty. Knowing the required repayment during the fixed period can make household budgeting easier, particularly when cash flow is tight or a borrower wants protection from short-term rate rises.
Protection From Variable-Rate Increases
If the lender increases variable rates during your fixed term, the rate on your fixed portion remains unchanged. That protection applies only until the fixed term ends.
Less Exposure to Short-Term Rate Movements
Some borrowers value knowing that market changes will not immediately alter the repayment on the fixed portion. This can provide breathing room during a period of parental leave, business transition or another predictable change in household finances.
Disadvantages of a Fixed Loan
You May Miss Out if Rates Fall
If variable rates fall below your fixed rate, you will generally continue paying the agreed fixed rate until the fixed period ends. Fixing therefore protects against one direction of rate movement but gives up the benefit of the other.
Extra Repayments May Be Restricted
Fixed loans commonly limit how much you can repay above the required amount. The rule differs by lender and product.
For example, CommBank currently states that its fixed-rate home loans allow up to $10,000 in additional repayments per fixed-term year before an early repayment adjustment and administrative fee may apply.[5] This is one lender's current rule—not a standard limit across the market.
If you expect to receive a bonus, inheritance, property-sale proceeds or another large lump sum, check the fixed-loan repayment limit before choosing the product.
Offset and Redraw May Be Limited
Many fixed-rate products do not provide a full offset account or access to redraw. Some lenders offer partial offset arrangements or other variations, so the actual product terms matter.
Losing these features can be significant if you maintain substantial savings or want regular access to extra repayments.
Break Costs May Apply
A break cost, early repayment adjustment or similar charge may apply if you:
repay the fixed loan early;
refinance during the fixed period;
sell the property and discharge the loan;
switch the fixed portion to another product;
exceed an additional-repayment limit; or
make another change that ends or alters the fixed-rate agreement.
The amount may be difficult to estimate in advance because it can depend on the remaining fixed term, the amount repaid and movements in relevant interest rates. CommBank explains that it may charge an early repayment adjustment when it incurs a loss as a result of a borrower breaking a fixed-rate contract.[7]
Do not assume the fee will be small. Request an up-to-date estimate from the lender before making a change.
What Happens When the Fixed Period Ends?
This is one of the most important parts of a fixed-rate decision.
When the fixed term expires, the loan will generally convert to the lender's applicable variable rate unless you select another option. That variable rate may be materially different from the fixed rate you have been paying.
Before the expiry date:
Check the rate that will apply automatically.
Ask the lender whether another fixed term is available.
Compare the revert rate with suitable options from other lenders.
Calculate repayments using several rate scenarios.
Review whether you now need offset, redraw or extra-repayment flexibility.
Allow enough time to refinance if changing lenders is worthwhile.
The end of a fixed period is not simply an administrative event. It is an opportunity to review the full loan.
What Is a Variable-Rate Home Loan?
A variable-rate home loan has an interest rate that can change during the loan term. If the lender increases or decreases the rate, the interest charged and required repayments may change.
The Reserve Bank explains that the cash rate strongly influences other interest rates, including household lending rates.[2] However, a lender's home loan rate is not the cash rate. Lenders also consider funding costs, competition, risk, operating costs and commercial decisions. A lender does not have to change every variable home loan rate by the same amount or at the same time as a cash-rate movement.
Advantages of a Variable Loan
You May Benefit if Rates Fall
If the lender reduces the variable rate applying to your loan, the interest charged should reduce, all else being equal. Your required repayment may fall, or you may be able to maintain the same payment and reduce the principal faster, depending on lender processes and your instructions.
Greater Repayment Flexibility
Variable loans commonly allow larger or unlimited extra repayments, although product terms still need to be checked. Extra repayments can reduce the balance on which future interest is calculated and may shorten the loan term.[4]
More Access to Offset and Redraw
Offset accounts and redraw facilities are more commonly attached to eligible variable-rate loans.
Moneysmart explains that an offset is a separate transaction account linked to a home loan. Its balance reduces the portion of the linked loan on which interest is calculated.[3]
A redraw facility may allow access to eligible extra repayments made directly to the loan. Access remains subject to the lender's terms, so redraw should not be treated as identical to cash held in a separate bank account.
Usually Easier to Change
It is generally easier to refinance, pay out or switch a variable loan without a fixed-rate break cost. Discharge, application, valuation, settlement or switching costs may still apply, and the financial benefit should be calculated before changing loans.
Disadvantages of a Variable Loan
Repayments Can Increase
If the lender raises your rate, the required repayment may increase. This can place pressure on a household that has borrowed close to its comfortable limit.
The effect becomes more significant with a larger balance and longer remaining term. A rate increase that appears small in percentage terms can produce a noticeable monthly cost.
Budgeting Is Less Predictable
You cannot know exactly what a variable repayment will be several years from now. Borrowers should maintain room in the budget rather than relying on the current required payment remaining unchanged.
Features Can Increase the Cost
A variable loan with offset, package benefits or other features may have a higher rate or additional fees than a basic loan. Moneysmart recommends comparing the cost of features with how much you are genuinely likely to use them.[1]
An offset account is valuable only while money remains in it. Paying a higher rate or annual package fee for an offset with a consistently low balance may not produce a net saving.
What Is a Split Home Loan?
A split home loan divides your borrowing into two or more loan accounts. One portion is usually fixed and the remaining portion is variable.
For example, a borrower with a $600,000 loan could choose a 60/40 split:
$360,000 fixed for an agreed period; and
$240,000 variable.
If variable rates rise, only the repayment on the $240,000 variable portion is directly exposed during the fixed period. If variable rates fall, only that portion receives the potential benefit. The $360,000 fixed portion remains at its contracted rate until the fixed term ends.
Moneysmart describes a split loan as a partially fixed arrangement and notes that borrowers may choose the division, such as 50/50 or 20/80.[1] The lender must still offer the chosen structure and the application must meet its requirements.
Advantages of a Split Loan
Partial Repayment Certainty
The fixed portion provides some protection from variable-rate rises. Because the entire debt is not fixed, the household keeps some exposure to rate reductions and flexible features.
A Place for Extra Repayments
Borrowers who expect to pay more than a fixed-loan allowance can direct eligible extra repayments to the variable portion. The aim may be to size the variable portion so it can absorb likely savings and lump sums during the fixed term.
Potential Offset Access
Where available, an offset account may be linked to the variable portion. This can allow savings to reduce interest while remaining accessible.
Less Reliance on a Single Rate Decision
A split loan avoids placing the entire balance on one side of the fixed-versus-variable decision. This may suit borrowers who want some certainty but are uncomfortable locking in the whole loan.
Disadvantages of a Split Loan
More Accounts to Manage
You will have at least two loan portions, potentially with different rates, repayments, statements and features. The total cost needs to be considered across the entire structure.
Fixed-Loan Restrictions Still Apply
The fixed portion may still have extra-repayment limits, restricted redraw and break costs. A split loan reduces the amount subject to those restrictions; it does not remove them.
The Split Can Be Poorly Matched to Your Savings
If the variable portion is too small, you may not have enough flexible loan balance to make the extra repayments you expect. If it is too large, more of your debt remains exposed to rate increases than you may be comfortable with.
Separate Fees May Apply
Some lenders may charge fees at the package, account or loan-split level. Ask for the total annual and upfront cost of the complete structure.
How Do You Choose the Split Percentage?
There is no universal 50/50 rule. The split should reflect your expected cash flow and tolerance for changing repayments.
Start by considering:
How Much Certainty Do You Need?
Estimate the maximum repayment increase your budget could absorb. A household that needs greater certainty may prefer a larger fixed portion. A household with substantial surplus income and a strong emergency buffer may be comfortable with more variable exposure.
How Much Do You Expect to Keep in Offset?
If you expect to hold $80,000 in savings but only place $30,000 of the loan on the variable side, some of the offset balance may not produce an additional interest benefit once it fully offsets that portion. Product calculations and limits vary, but this illustrates why the split should be coordinated with expected savings.
How Much Extra Do You Expect to Repay?
Estimate regular extra repayments and likely lump sums over the fixed term. The variable portion may need to be large enough to accept those amounts without forcing you to exceed the fixed portion's limit.
Could You Sell or Refinance During the Fixed Term?
If a move, sale, renovation, relationship change or refinance is reasonably possible, a large fixed portion may reduce flexibility and expose more of the debt to potential break costs.
When Will Your Circumstances Change?
Match the fixed period to known events where practical. A five-year fixed term may not suit a borrower expecting to sell in two years. A short fixed term may not deliver the length of certainty another household needs.
CommBank's explanation of split lending similarly suggests considering the desired balance between certainty and flexibility, expected personal changes and the length of fixed term the borrower is prepared to commit to.[6]
Fixed Rates Are Not a Forecasting Tool
A common mistake is choosing a loan entirely around a prediction that rates will rise or fall.
Fixed rates are generally priced using market expectations and lender funding considerations. Future rate movements are uncertain, and the lowest-cost choice can only be known afterwards.
A more practical question is:
If variable rates rise, how much certainty do I need—and what flexibility am I willing to give up to obtain it?
Fixing can still be worthwhile even if variable rates later fall, because certainty itself may have been valuable to the household. Conversely, remaining variable can still be a reasonable decision even if rates later rise, provided the borrower deliberately chose flexibility and could absorb the change.
The decision should be judged against your objectives and budget at the time, not only with hindsight.
How Much Could a Rate Change Affect Repayments?
The impact depends on the loan balance, remaining term, repayment type and size of the rate movement.
As a simple illustration, a 0.50 percentage-point increase on a large variable balance can add a meaningful amount to the monthly repayment. On a split loan, only the variable portion is immediately exposed while the fixed period continues.
Use a mortgage calculator to compare repayments at:
the current rate;
0.50 percentage points higher;
1 percentage point higher; and
a rate that would materially test your household budget.
Moneysmart's mortgage calculator allows borrowers to compare repayments at different rates and see how small rate differences can affect long-term loan costs.[9]
Calculators are estimates. They do not predict future rates, reproduce every lender's calculation or include every fee.
Offset Accounts and the Fixed-versus-Variable Decision
Borrowers with substantial savings should compare the likely offset benefit before fixing the entire loan.
Suppose you have a $500,000 loan and maintain $50,000 in a full offset linked to an eligible variable loan. Interest is generally calculated on the difference—$450,000—while the money remains in the offset.[3]
If the whole loan is fixed under a product with no offset, you may lose that benefit. If you split the loan, an offset might be linked to the variable portion, subject to lender rules.
Compare:
the variable rate with and without offset;
the fixed rate;
annual package and account fees;
your realistic average offset balance;
whether the offset is full or partial; and
which loan portion the offset can be linked to.
Do not select an offset because it sounds useful. Calculate whether it is likely to save more than it costs.
Redraw and Extra Repayments
If paying the loan down quickly is a priority, compare repayment rules carefully.
Moneysmart notes that extra repayments can reduce interest and help repay a mortgage faster, but borrowers should check whether the lender permits them and whether fees apply.[4]
Ask:
Is there a limit on extra repayments?
Is the limit measured by calendar year, loan year or fixed-term year?
Can extra repayments be redrawn?
Are there minimum redraw amounts or fees?
Could the available redraw reduce over time?
What happens to redraw if the loan changes from variable to fixed?
Which portion should receive extra repayments on a split loan?
An offset account and redraw facility can both reduce interest, but they are not the same. Offset money remains in a separate account. Redraw involves accessing eligible extra repayments already made to the loan, subject to lender terms.
Do Not Compare the Interest Rate Alone
When comparing fixed, variable and split options, examine the complete cost and structure:
interest rate;
comparison rate;
application and settlement fees;
annual or package fees;
offset fees;
valuation and legal fees;
discharge or switching fees;
break-cost risk;
extra-repayment limits;
redraw access;
revert rate after the fixed period;
loan term; and
the cost of any features you will use.
ASIC explains that a comparison rate combines the interest rate with most fees and charges to help consumers compare credit products, although it does not include every possible cost.[8]
A comparison rate is useful, but it is calculated using a specified loan amount and term that may differ from yours. It also cannot capture the personal value of features, the benefit of your expected offset balance or a future break cost that is not known.
Which Loan Type May Suit Different Borrowers?
The following examples are general only.
A Fixed Loan May Suit You If:
stable repayments during the fixed period are a high priority;
you could struggle with a near-term repayment increase;
you do not expect to make large extra repayments;
you are unlikely to sell or refinance during the fixed term;
you do not require an offset or flexible redraw; and
you understand the revert-rate and break-cost risks.
A Variable Loan May Suit You If:
you can absorb repayment changes;
you value offset, redraw or extra-repayment flexibility;
you expect to pay the loan down aggressively;
you may sell, refinance or change the loan structure;
you want to benefit if your lender reduces the rate; and
you are comfortable with less repayment certainty.
A Split Loan May Suit You If:
you want some protection from rate increases without fixing the whole debt;
you want a variable portion for offset savings or extra repayments;
your budget can handle movements on part of the loan;
you want to reduce reliance on a single rate choice; and
the fixed period aligns with your expected plans.
These indicators are not a recommendation. Two borrowers with identical incomes and loan balances may reasonably choose different structures because their savings, expenses, plans and risk tolerance differ.
Questions to Ask Before Choosing
Ask your mortgage broker to explain:
What are the fixed, variable and split options available for my situation?
What would the initial repayment be under each structure?
How would the variable repayment change at higher rates?
What fixed periods are available?
What rate will apply when the fixed period ends?
Can I make extra repayments, and what are the limits?
Is redraw available on each portion?
Can an offset account be linked, and to which portion?
Is the offset full or partial?
What package, account and split-loan fees apply?
When could a break cost be charged?
How might my expected savings affect the best split percentage?
What happens if I sell or refinance earlier than planned?
Can the loan structure be changed later, and at what cost?
The broker should compare the total structure, not simply present the product with the lowest initial rate.
How Homefront Mortgages Can Help
Choosing between fixed, variable and split lending requires more than a view on where rates may go. The structure needs to match your budget, savings, future plans and preferred level of flexibility.
Homefront Mortgages can help you:
compare fixed, variable and split options across a range of lenders;
model repayments under different rate scenarios;
assess the value of offset and redraw features;
check extra-repayment limits and fixed-rate conditions;
calculate the likely effect of different split percentages;
compare rates, fees, features and revert-rate risks; and
choose a loan structure that aligns with your circumstances and goals.
The right loan is not simply the one with the most attractive rate today. It is the one structured to remain practical as your finances and the lending market change.
If you are buying, refinancing or reviewing an existing fixed period, contact Homefront Mortgages to discuss your options.
Important Information
This article provides general information only and does not take into account your objectives, financial situation or needs. It is not financial, tax or legal advice. Interest rates, fees, lending criteria and product features vary between lenders and may change. Fixed-rate break costs and early repayment adjustments depend on the lender's terms and circumstances at the time. Calculations and examples are illustrative only. Before acting, review the relevant loan documents and seek advice from appropriately qualified professionals where required.
References
Moneysmart, Choosing a home loan, accessed 17 August 2026.
Reserve Bank of Australia, The transmission of monetary policy, accessed 17 August 2026.
Moneysmart, Mortgage offset accounts, accessed 17 August 2026.
Moneysmart, Pay off your mortgage faster, accessed 17 August 2026.
Commonwealth Bank, Fixed or variable home loan: What's the difference?, accessed 17 August 2026.
Commonwealth Bank, What is a split home loan?, accessed 17 August 2026.
Commonwealth Bank, What is an Early Repayment Adjustment?, accessed 17 August 2026.
Australian Securities and Investments Commission, National Credit Code—comparison rates, accessed 17 August 2026.
Moneysmart, Mortgage calculator, accessed 17 August 2026.